Background
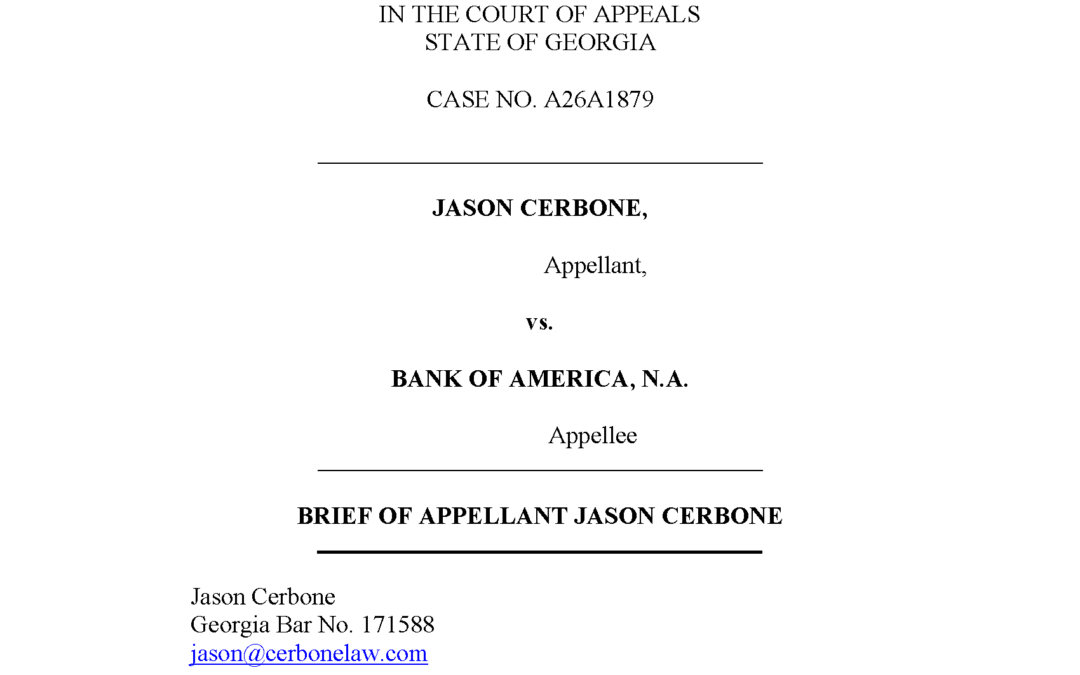
The case is Jason Cerbone v. Bank of America, N.A., Georgia Court of Appeals, No. A26A1879. The brief was filed May 18, 2026. Jason Cerbone is a lawyer. He is his own lawyer here. This time he is the one being sued.
Bank of America sued Jason in March 2023. It was over a credit card, a University of Georgia card. The bank said he owed $74,471.69. He said he had the card. He said he did not owe that much. The fraud and the unauthorized charges began in November 2019. There was a pattern of unauthorized charges (mostly Amazon Marketplace, Amazon Digital Services, Audible, Kindle, plus, QuickBooks, and Xero charges). On November 21, 2019 Cerbone reported to Bank of America fraud charges in the amount of $26,008.09 initially and eventually, by 2023, $41,994.03.
Cerbone documented an extensive paper trail: multiple letters to Bank of America, a Savannah Police Identity-Theft report, a Federal Trade Commission (FTC) Identity Theft Report, a Consumer Financial Protection Bureau (CFPB) complaint, the big three credit-bureau freezes, and repeated follow-up — yet the Bank repeatedly denied his fraud claims with boilerplate letters that never identified the specific charges or merchants at issue, and never explained its investigation.
He told Bank of America. He wrote many letters. He froze his credit. He kept writing. It is all in the record.
Bank of America said no. It said no in form letters. The letters did not name the charges. They did not name the merchants. They did not say how the bank had looked into anything.
Court Procedure
In June 2023 the bank asked for summary judgment. Cerbone fought it. His father, also a lawyer, handled it first. In September 2024 Cerbone took it over himself. In January 2025 he asked to add a counterclaim. It was one he should have filed at the start. It claimed breach of contract. It claimed breach of good faith and fair dealing. It claimed violations of the FDCPA and of Regulation Z under the Truth in Lending Act. He asked for a jury.
The bank did not answer for almost eleven months. In February 2026 Judge Coolidge said no to the counterclaim. She did not say why. Judge Coolidge gave the bank partial summary judgment. That settled liability. Judge Coolidge set a hearing on damages. The hearing never came. The appeal came first.
Two Errors
Denial of leave to add the counterclaim was an abuse of discretion. First is the counterclaim. Georgia law liberally allows amendments to add compulsory counterclaims absent a showing of prejudice Georgia lets a party add a compulsory counterclaim unless the other side is hurt by it. The cases say so: MCG Development Corp. v. Bick Realty, Talbot Construction v. Triad Drywall, SRM Group v. Travelers. The bank never said it was hurt. Discovery had barely started. The counterclaim came from the same card and the same charges. The Bank never argued prejudice, the case was still early in discovery, and the proposed counterclaim arose from the same transaction as the Bank's claim, so the trial court's unexplained denial was reversible error.
Summary judgment on liability was improper, and even if not, denying a jury trial on damages was error. The second is summary judgment. Regulation Z, 12 C.F.R. § 1026.12, limits what a cardholder owes when someone else runs up charges without the card. It can wipe that debt out. Before a bank can hold a cardholder liable, it must investigate, and investigate reasonably. The rule lists the steps. Bank of America never showed the court it took them. Cerbone had the card the whole time. A thief does not need the card to buy Kindle books, nor anything on the internet.
Regulation Z also lets a cardholder hold back payment on a disputed charge when the bank does not resolve the dispute. So how much he owes, if anything, is a question of fact. Questions of fact are not for summary judgment.
And say the bank was right about liability. Damages still belong to a jury. The Georgia Constitution says so in Article I, Section I, Paragraph XI(a). O.C.G.A. § 9-11-56(c) says so. Atlanta Oculoplastic Surgery v. Nestlehutt says so. Sibley v. Fulton DeKalb Collection Service says so. A hearing is not a jury.
Cerbonbe asks the court for three things. Reverse the March 9, 2026 order. Reverse the February 19, 2026 order. Send the case back for a jury trial.